As a first home buyer in Bankstown, your main steps are working out your deposit, checking which NSW and Australian Government schemes may apply, and understanding how much lenders may let you borrow. The rules are the same across NSW, but local property prices decide which schemes and price caps are relevant to you. This guide walks through each step and links to our more detailed NSW guides where they help.
Buying your first home in Bankstown: what is different
The rules for first home buyers are set by the NSW and Australian Governments, so they are the same in Bankstown as anywhere else in NSW. What changes is how they apply to the property you want.
Bankstown sits within the Sydney area for scheme purposes. That matters because property price caps for Sydney are different from regional NSW. Whether you are looking at a unit near the town centre or a house in a surrounding suburb, the purchase price decides which support you may be eligible for.
Many Bankstown buyers also come from multicultural and multi-generational households. Buying with family, using a family guarantee, or buying on a visa all have their own rules, so it is worth checking these early.
Deposit and government schemes in NSW
You may not need a 20% deposit. Several schemes can reduce the deposit or upfront costs for eligible first home buyers. The main ones are:
- Australian Government 5% Deposit Scheme: eligible buyers may purchase with a 5% deposit without paying Lenders Mortgage Insurance (LMI). Property price caps apply, and Bankstown falls under the Sydney cap.
- Help to Buy: an Australian Government shared-equity scheme where eligible buyers may purchase with a minimum 2% deposit. Income limits and price caps apply.
- NSW First Home Buyers Assistance Scheme: a stamp duty exemption or concession for eligible buyers, depending on the property's value.
- First Home Owner Grant (FHOG): a NSW grant for eligible buyers of new homes, subject to value caps.
Each scheme has its own eligibility rules, and some cannot be combined. For full details, read our guides on deposits and government support in NSW and the Help to Buy scheme.
Not sure which schemes may apply to you? See how we help on our First Home Buyers page, or book a first home buyer consultation to check your options.
Borrowing capacity and what lenders look at
Your borrowing capacity is the amount a lender may be willing to lend you, based on what you earn, what you spend and what you already owe. Each lender calculates it differently, so the figure can vary between lenders.
Lenders usually look at:
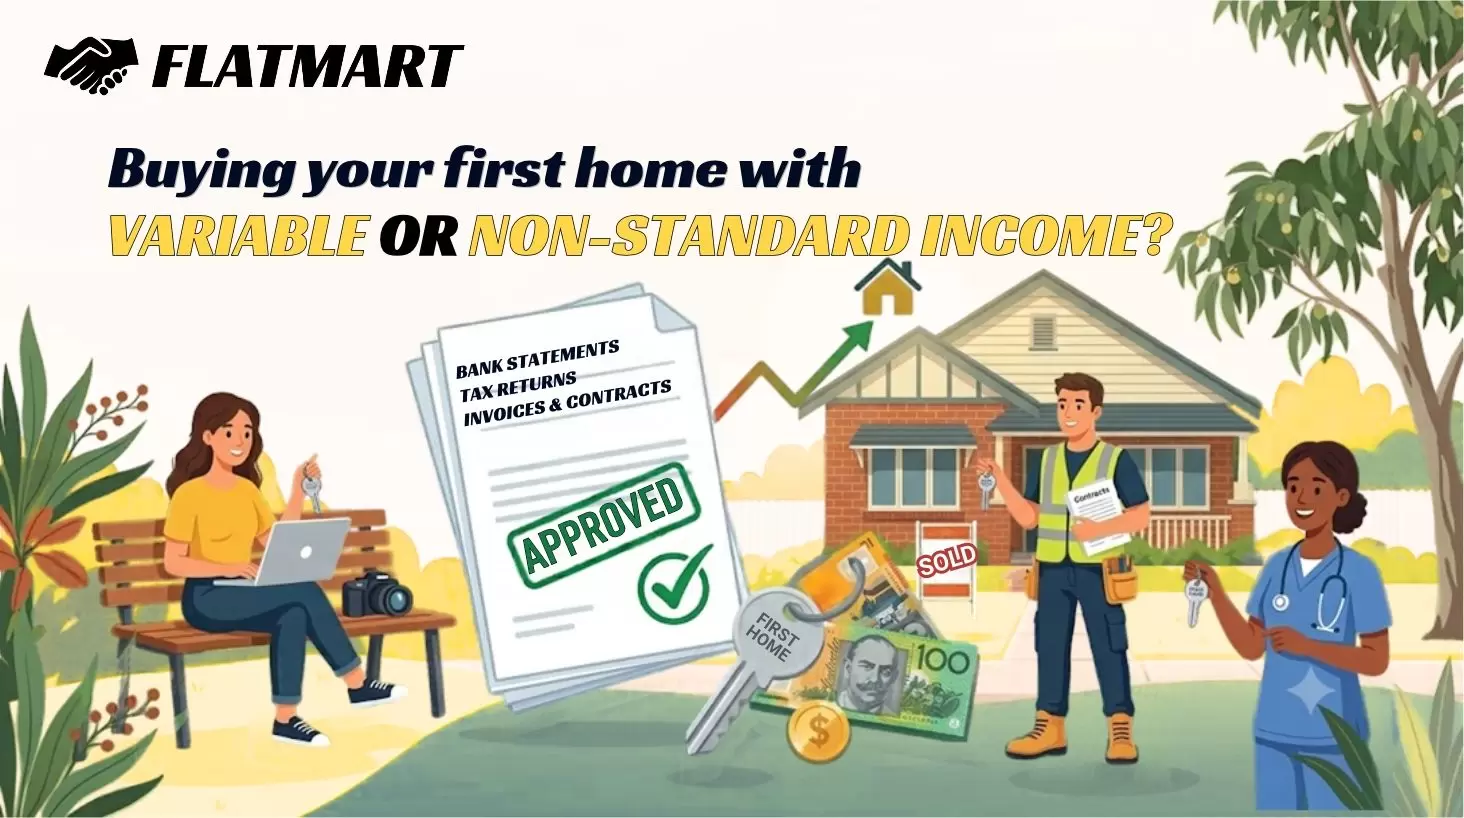
- Income: salary, and how stable it is. Casual, contract and self-employed income is assessed differently.
- Living expenses: your regular spending, checked against your bank statements.
- Existing debts: car loans, personal loans and credit cards. Lenders count the full card limit, even if you owe nothing.
- Deposit and savings history: how much you have saved and how you saved it.
- Credit history: your record of paying bills and debts on time.
Lenders also check whether you could still afford repayments if interest rates rose. If your income is not a standard salary, see our guide to buying with variable or non-standard income.
Common first-timer mistakes
Most first home buyer mistakes are about timing and preparation, and they are easy to avoid.
- House-hunting before pre-approval. Consider seeking pre-approval first, so you have an indication of your borrowing range. Pre-approval is conditional and is not final approval.
- Forgetting upfront costs. Allow for stamp duty (if it applies), conveyancing, building and pest inspections, loan fees and moving costs.
- Taking on new debt. A new car loan, phone plan or buy-now-pay-later account just before you apply can reduce what you can borrow.
- Changing jobs at the wrong time. Some lenders want to see time in your current role or industry.
- Assuming every lender is the same. Policies differ a lot, especially for deposits, visas and self-employed income.
- Not checking scheme rules early. Price caps and eligibility rules change, so check them before you sign a contract.
How a local mortgage broker can help
A Bankstown mortgage broker can help you compare suitable loan options from their lending panel, check which schemes you may be eligible for, and manage your application through to settlement. Brokers must act in your best interests and tell you how they are paid.
Flatmart is based in nearby Canley Vale and works with first home buyers across south-west Sydney. We can also help if you are buying on a visa or as a permanent resident. Learn more on our Bankstown mortgage broker and First Home Buyers pages.
Next step: talk to a first home buyer broker
If you are thinking about buying your first home in Bankstown, a short conversation can help you understand your deposit, the schemes you may be eligible for and how much lenders may consider lending you.
- Book a first home buyer consultation by phone, video call or at our Canley Vale office
- See how we help first home buyers on our First Home Buyers page
- Or call 0485 937 168 to talk to a Flatmart mortgage broker
Ready to get started?
Book a chat with a Finance & Mortgage Broker at Flatmart today.
Last reviewed: November 2026
This article provides general information only and does not take into account your objectives, financial situation or needs. Scheme eligibility, lending criteria, fees and charges apply, and all loans are subject to lender approval.